We’re officially nine months into the year. The asset class, sector, and global market quilts are up to date for Q3 2026. Links to the updated versions are below:
You can download copies here or save the images below.
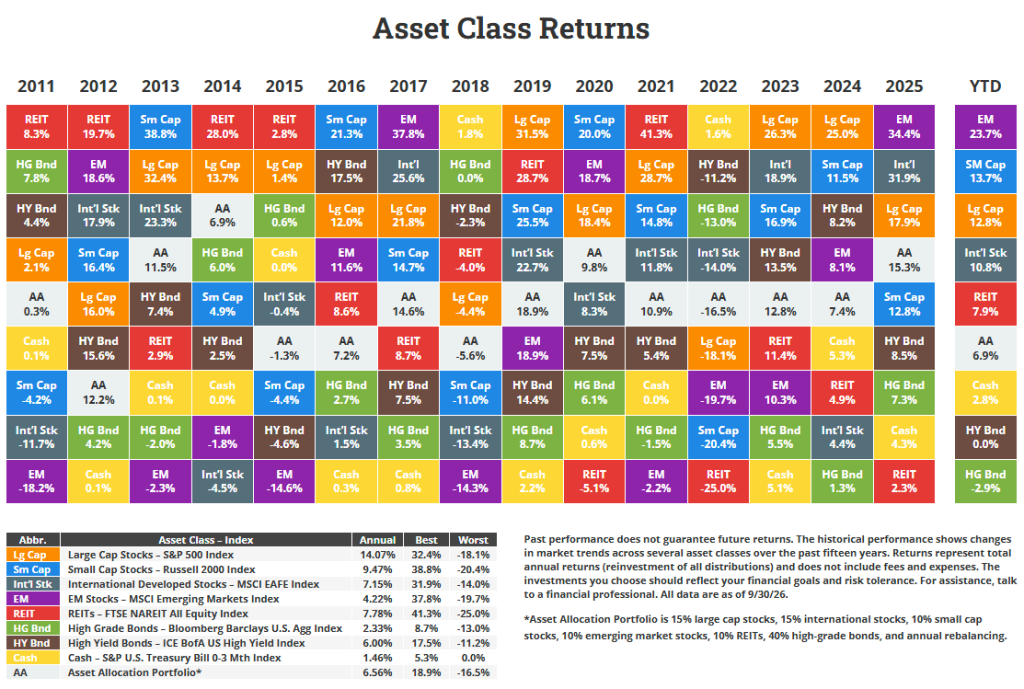
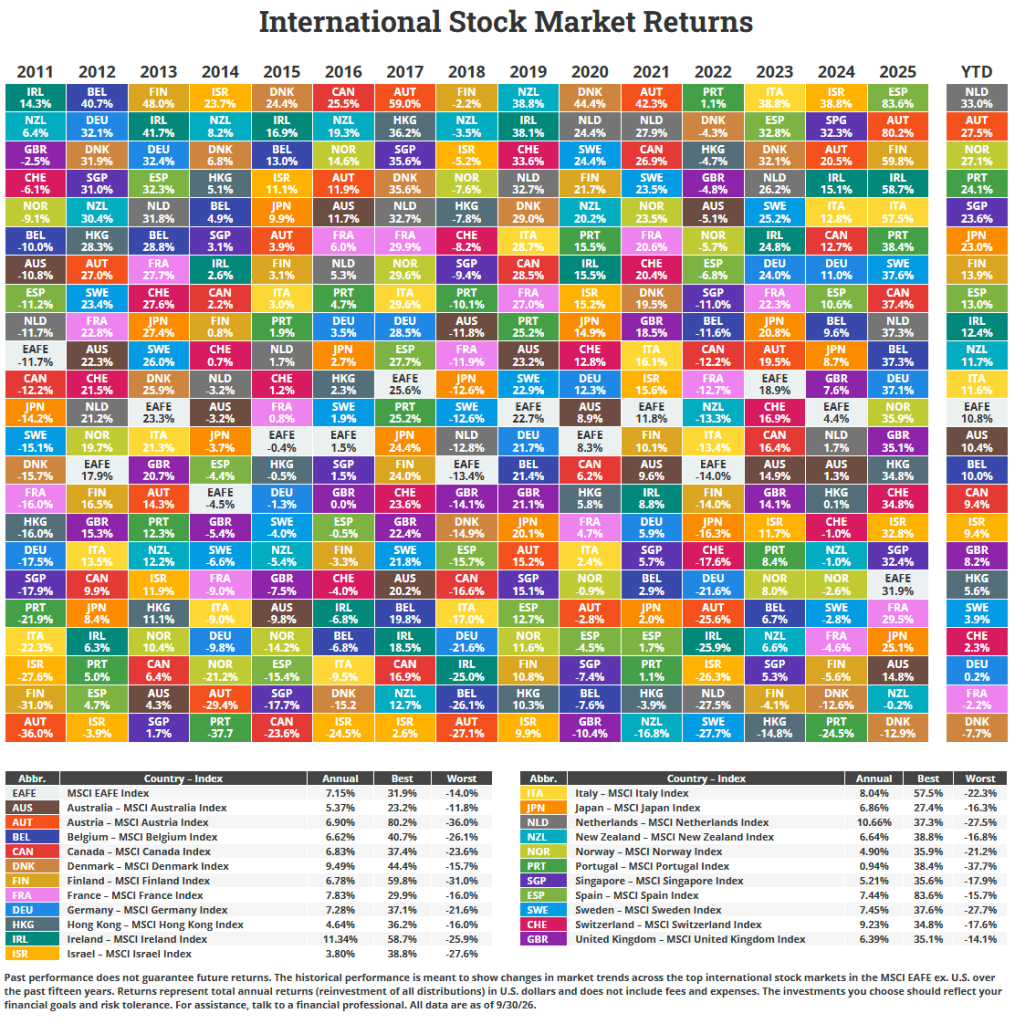
Stocks have done well so far this year. While broader markets are higher on the year, most were relatively unchanged in the third quarter. Emerging markets still lead with a 24% total return. The two exceptions were REITs and US small caps. Both fell in Q3 but are still positive year to date.
The energy sector ended the quarter on top with a 40% return through the third quarter followed by the tech sector. All other sectors underperformed the S&P 500’s 13% return.
The big story at the end of Q3 is all about the boring part of our portfolio. Bonds and interest rates grabbed headlines. Year-to-date, 10-yr Treasury yields have risen about 100 bps or 1 percentage point. That’s a move from 4.2% to start the year to 5.2% today.
It’s no surprise that the US Agg index is down on the year. Though, the loss of -3% is manageable. But the concern of a repeat of 2022’s bond losses, where Treasury rates more than doubled in less than 12 months, might be replaying in investors’ minds.
The good news is that every new dollar going into high grade bonds, like US Treasuries, earns more interest now than 9 months ago. The bad news is that bond prices move inversely to interest rates.
Bond price volatility is linked to duration. The rule of thumb is for every 1 percentage point change in interest rates, expect bond prices to move in the opposite direction roughly equal to 1% times duration.
If the large swings in bond prices made you uncomfortable in 2022, maybe shorter duration bonds would allow to sleep easier.
But if you can stomach more short-term volatility, it’s good to know that starting bond yields are a good determinant of long-term returns.
I’ll have more on the Q3 numbers next week. Here’s the quilts.